By Brian French, FlFinancialNews.com | November 14, 2026
Quick Answer
Nvidia now trades near 11 to 13 times forward earnings, its lowest valuation in more than a decade, after Jensen Huang’s resignation. The financial data has barely changed: revenue is doubling, gross margin is 75%, and supply is committed through 2027. The stock price is following the story, not the numbers.
The Story the Market Is Trading
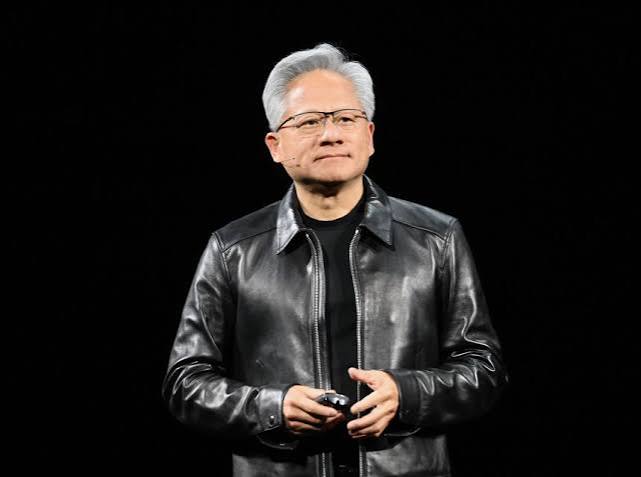
The headlines this week have been about one man. Huang stepped down Thursday as scrutiny mounted over extramarital affairs, and one of the women involved is a suspected Chinese spy. Congressional Republicans are pressing to get him in front of lawmakers before the January change of control.
The stock reacted accordingly. Friday’s close left Nvidia’s market value under $4 trillion, a level last seen in July 2025. The week’s 12.75% loss extended the losing streak to six weeks, the longest run since 2012.
Very little of that coverage mentions an income statement.
The Door Ding Discount
Picture a new car on a dealer’s lot marked down to half price because it has a ding in the door. The engine is the same. The transmission is the same. The warranty is the same. Most buyers would check under the hood, confirm the damage is cosmetic, and take the deal.
That is close to what the market is offering in Nvidia. As recently as September, the shares carried a forward multiple of 25. Reuters now puts it near 12. The price paid for each dollar of expected earnings has been cut roughly in half. The shares themselves sit 32% below their October 6 record.
The fair question is whether this is a door ding or engine damage. That is what the financial data is for.
What the Financial Data Says
| Metric (Q2 fiscal 2027) | Result |
|---|---|
| Revenue | $96.2 billion, up 106% |
| Data Center revenue | $89.0 billion, up 117% |
| Gross margin | 75.0% |
| Operating margin | 66.2% |
| Q3 revenue guidance | $108.0 billion |
Sales for the quarter ended July 26 reached $96.2 billion, a 106% gain over the prior year, with gross margin at 75.0%. Operating margin came in at 66.2% and net margin at 62.0%. Management’s outlook for the current quarter calls for $108.0 billion, give or take 2%, with no China data center compute revenue assumed.
Few companies of any size have ever combined that growth rate with those margins. The engine is running.
Selling $100 Bills for $25
A 75% gross margin is easy to read past. Put it in plain terms. Nvidia sells a $100 bill that cost $25 to make. After research, salaries, overhead and taxes, about $62 of that $100 is still left as profit.
Now compare that with businesses most people know.
| Business | Gross margin | Kept as profit per $100 of sales |
|---|---|---|
| Nvidia | 75.0% | About $62 |
| ExxonMobil | About 24% | About $9 |
| Walmart | 24.9% | About $3 |
| Typical eBay seller | Varies | $8 to $25 (estimate) |
Walmart. The world’s largest retailer runs on a 24.9% gross margin and a 3.1% net margin. Out of every $100 rung up at the register, about $75 goes to buying the merchandise and about $3 is left at the end. Walmart has to sell $2,000 of goods to earn what Nvidia earns on $100.
An oil company. ExxonMobil’s latest figures show gross margin of 23.9% and net margin of 8.9%. That is after drilling wells, running refineries and riding the price of crude up and down.
An eBay seller. Anyone who has sold on eBay knows the math. The platform’s cut on most categories runs about 13.6% of the sale plus a per-order fee. Then come the cost of the item, shipping and packaging. One industry benchmark puts the average seller’s net margin at 8% to 25%.
These are good businesses. Walmart and Exxon are among the best-run companies in the world. And they keep $3 and $9.
A 75% margin almost never happens in a business that makes a physical product. Manufacturing is supposed to be a grind of materials, factories and competitors cutting price. Some software companies reach margins like this, because copying code costs nothing. Nvidia does it with hardware that has to be fabricated, packaged and shipped.
Put the two facts together. The company sells $100 bills for $25, and every one it can print for the next two years is already sold.
One Person Left. The Company Stayed.
Nvidia is not one person. Tens of thousands of employees came to work this week: the engineers who design the chips, the software teams, the sales force and the supply chain managers. None of them resigned on Thursday.
The work they do is already set for years. Chips take years to design, so the products Nvidia will sell in 2027 and 2028 are essentially decided. Blackwell is in full ramp, with Rubin Ultra slated for 2027 and Feynman for 2028. The board itself said operations, customer commitments and the roadmap should carry on without interruption.
Every chief executive is replaced eventually. Founders retire, step aside or pass on, and investors usually have years to get used to the idea. What made this a story was the suddenness. A planned handoff announced a year in advance would have been a one-day headline. The same change in a single week, wrapped in scandal, became a market event.
But suddenness is a feature of the story, not of the business. The people, products and customers are the same ones that were there last Friday.
The Valuation Gap With AMD
This is where “buy low, sell high” becomes more than a slogan. Published figures vary by source and by which fiscal year is used, but the ranking is consistent.
| Company or benchmark | Forward P/E |
|---|---|
| Nvidia | About 11 to 13 |
| Broadcom | About 16 to 20 |
| S&P 500 | About 19 to 20 |
| AMD | About 27 to 35 |
TradingView data shows a Thursday morning low of 11.9 times, the bottom of a record that starts in May 2016. That left Nvidia cheaper than UPS at 14.1 times.
The comparison with AMD is the striking one. AMD commands 27 times forward earnings against Nvidia’s 13, even though its revenue is growing more slowly. Another tally has AMD at 34.8 times, more than triple Nvidia’s 10.5.
One caution on the math. The forward multiple depends on analyst estimates being right. On trailing earnings, Nvidia’s P/E was about 20.8 as of November 12, which is still modest for a company doubling its revenue.
Demand Has Not Changed
The key question is whether the scandal changes what customers buy. So far, the evidence says no.
- Orders: Four Taiwan supply chain executives told local media that orders through 2027 are unchanged, and one said some extend into 2028.
- Spending: Kress told investors in August that the top five hyperscalers should spend nearly $800 billion in 2026 and $1.3 trillion in 2027, against a cloud backlog above $2 trillion.
- Growth: Management’s August outlook pointed to roughly 70% revenue growth in fiscal 2028 and called it supply-constrained.
- Estimates: Earnings forecasts stayed broadly flat over the past month while the shares dropped about 27%, so nearly all of the decline came from a shrinking multiple.
The earnings did not fall. The price investors will pay for them did.
The Real Headline: Sold Out for Two Years
The market spent this week on the wrong story.
A chief executive leaving is the most ordinary event in corporate life. It happens somewhere every week. Every company on earth will replace its leader, and every one of them survives the day it happens.
Now consider what is not ordinary. Nvidia’s order book is committed through 2027 and into 2028, and its growth is capped by supply. Customers want more than the company can build. Every chip is sold before it exists.
Most of the people setting Nvidia’s price have never owned a business, so they may not grasp how rare that is. Ask anyone who has. An owner starts each year with a few months of orders and a knot in his stomach about the rest. Six months of firm demand is a good year. Twelve months is a career highlight.
Two years, sold out, at a 75% gross margin, is something almost no business owner will see in a lifetime. It is the thing every owner lies awake wishing for. There is no selling left to do. The only question is how fast the product can be made.
That is the story. One person leaving is common and temporary. A two-year sellout is rare and worth a fortune. The market has priced the common event as a catastrophe and the rare one as if it were nothing.
Scarcity like that should command a large premium. Instead the stock trades at 11 to 13 times forward earnings, below the average company in the S&P 500. In this writer’s opinion, it deserves something closer to 30 times.
The Risks Are Real
A careful buyer still inspects the car. Readers deserve the other side.
- Leadership: Huang ran Nvidia with about 60 direct reports, no chief operating officer and no public succession plan. Chief Financial Officer Colette Kress is interim CEO while keeping her finance role.
- Washington: The relationship has raised concerns that a Singapore company diverted restricted Nvidia chips to China. An investigation could lead to tighter export rules.
- Beyond 2028: The public roadmap ends in 2028 with Feynman, and after that someone other than Huang sets direction.
- Margins: Profits this large attract competition. AMD, Broadcom and the hyperscalers’ own chips are all aimed at that 75%.
- Estimates: GuruFocus flags the stock as a possible value trap despite its own model showing a deep discount. Morgan Stanley has warned that delayed data center builds could create a spending air pocket in 2028.
- Earnings: Nvidia’s announcement of the transition did not reaffirm guidance. Tuesday’s report is the first hard test.
Why This Matters to Florida Investors
Nvidia is one of the largest holdings in every S&P 500 index fund. Any Florida retiree or saver who owns a broad market fund owns Nvidia, whether they follow the news or not. Knowing whether a price drop reflects the business or the headlines is a practical skill, not an academic one.
Brian’s Take
I managed money for a living years ago, and the first rule never changed: buy low, sell high. It is easy to say and hard to do, because “low” only shows up when the news is terrible.
Think about that car with the door ding. Nobody wants to be seen driving off the lot in the one everybody is whispering about. So it sits there at half price while buyers pay full sticker for the model next to it. That is Nvidia and AMD this week.
Today’s market trades on narrative. One man left, and it happened fast, and fast makes a better story. But tens of thousands of people who design, build and sell the product are still at their desks. Every CEO is replaced eventually. Apple replaced Steve Jobs.
Here is what I want readers to hear, because I have owned businesses and most analysts have not. There are two fantasies every business owner has. The first is being sold out. The second is a margin so fat you can hardly believe it.
Being sold out for two years does not happen. I have never seen it. I have never met an owner who has seen it. If I had ever opened a year knowing that everything I could produce through the end of the next year was already sold, I would have thought I was dreaming.
Then there is the margin. Selling a $100 bill that cost you $25 does not happen either. Walmart keeps $3. Exxon keeps $9. Anybody who has sold on eBay knows what is left after fees and postage. Nvidia keeps $62. In a real business you get one of those fantasies for a little while, if you are lucky. Nvidia has both at the same time, at a size no company has ever reached.
That is the rare event in this story. Not the resignation. Wall Street is staring at the door ding and ignoring the fact that there is a line of buyers around the block, cash in hand, waiting two years for this car.
That is not an 11 times earnings business. To me it is a 30 times business.
I may be wrong about the timing. Scandals can run longer than anyone expects, and Tuesday’s earnings could disappoint. But investors who buy on financial data, and not on headlines, have usually been paid for their patience.
Frequently Asked Questions
What is Nvidia’s P/E ratio right now?
About 11 to 13 times forward earnings, depending on the source and fiscal year used. The trailing P/E is about 21.
Is Nvidia cheaper than AMD?
Yes, on forward earnings. AMD trades at roughly 27 to 35 times, about two to three times Nvidia’s multiple.
What is Nvidia’s profit margin?
Gross margin was 75.0% last quarter and net margin was 62.0%. Nvidia keeps about $62 of every $100 in sales.
How do Nvidia’s margins compare with Walmart and ExxonMobil?
Walmart’s net margin is about 3% and ExxonMobil’s is about 9%. Nvidia’s is about 62%.
Why did Nvidia stock fall?
Jensen Huang resigned as CEO on November 12 amid a personal scandal with national security questions. Earnings estimates have held roughly steady.
Can Nvidia operate without Jensen Huang?
Its products through 2028 are already designed and its workforce is intact. The open question is long-term direction under a permanent successor.
Is Nvidia’s chip supply sold out?
Supplier reports indicate orders are committed through 2027, with some into 2028. Management has described fiscal 2028 growth as limited by supply, not demand.
Why would a sold-out company deserve a higher multiple?
Committed demand for years removes most of the sales risk that ordinary businesses face, which investors normally pay a premium for.
When does Nvidia report earnings?
Tuesday, November 17, 2026, after the market closes.
Disclosure: This article is opinion and general information, not individualized investment advice. All investments carry risk, including loss of principal. Consult a licensed financial advisor before making investment decisions.
Sources and Further Reading
- NVIDIA Corporation, “NVIDIA Announces Financial Results for Second Quarter Fiscal 2027,” August 26, 2026
- CNBC, “Nvidia closes below $4T market cap for first time since July 2025 in Huang fallout,” November 13, 2026
- CNBC, “Nvidia is done with Jensen Huang. The fallout in Washington is just beginning,” November 13, 2026
- Benzinga, “Wall Street Now Values Nvidia Like a Package-Delivery Company, Data Shows,” November 2026
- Yahoo Finance, “NVIDIA Trades at 13 Times Forward Earnings After a 27% Slide,” November 2026
- Yahoo Finance, “NVIDIA Stocks Fall 2.27% as Interim CEO Kress Faces Tuesday Earnings Test,” November 13, 2026
- Macrotrends, “NVIDIA PE Ratio 2013-2026”
- Midgard Finance, “NVIDIA Revenue by Segment, Data Center Growth and Gross Margin,” November 2026
- VCP Scanner, “Walmart Inc. (WMT) Earnings History,” June 2026
- FullRatio, “XOM Exxon Mobil Margins,” 2026
- FlowLister, “How Much Does eBay Take,” 2026
- EcomCalcTools, “eBay Seller Profit Margin Benchmarks 2026”
- The Motley Fool, “AMD Stock Has Blown Past Nvidia This Year. Is It Still the Better Buy?” September 22, 2026
- The Motley Fool, “Nvidia Says Its Cloud Customers Are Sitting on a $2 Trillion Backlog,” September 3, 2026
- Kolytics, “Whose Fumble Caused the Tumble?” November 2026
- BankInfoSecurity, “Why Nvidia’s Biggest Risk After Huang’s Exit Lies Beyond 2028,” November 2026
- BigGo Finance, “AMD Stock Surges Over 250% in Four Years; Forward P/E Tops Nvidia’s by More Than Threefold,” November 2026